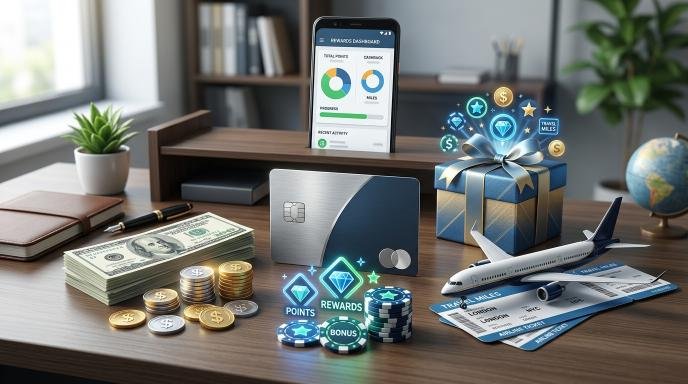
Credit cards are often more than just a convenient way to pay for everyday purchases. Many credit cards also offer rewards that can help cardholders get additional value from their regular spending. Depending on the card, these rewards may come in the form of cashback, points, airline miles, or welcome bonuses.
However, credit card rewards can sometimes be confusing. One card may offer 2% cashback, another may provide points for every dollar spent, while a travel card may offer miles and additional travel benefits.
Understanding how these reward systems work can help you compare credit cards and choose one that fits your spending habits.
What Are Credit Card Rewards?
Credit card rewards are benefits provided by a card issuer when you make eligible purchases with your credit card.
Instead of receiving nothing for your spending, you may earn a percentage of your purchase back as cashback or accumulate points or miles that can later be redeemed.
For example, if a card offers 2% cashback and you spend $500 on eligible purchases, you could earn approximately $10 in cashback.
The actual value of rewards depends on the card’s terms, eligible purchases, redemption options, and other conditions.
Cashback Rewards
Cashback is one of the easiest credit card reward systems to understand.
With a cashback card, you generally receive a percentage of eligible purchases back as a reward. The cashback rate can vary depending on the card and the type of purchase.
For example:
| Purchase | Spending | Cashback Rate | Potential Cashback |
|---|---|---|---|
| Groceries | $300 | 3% | $9 |
| Gas | $150 | 2% | $3 |
| Online Shopping | $200 | 2% | $4 |
| Other Purchases | $350 | 1% | $3.50 |
In this example, the total potential cashback would be $19.50.
Some cards offer a flat cashback rate on most purchases, while others provide higher rates in selected categories.
Flat-Rate Cashback
A flat-rate cashback card generally provides the same reward rate on eligible purchases regardless of category.
This can make rewards easier to manage because you do not need to remember which categories earn higher rewards.
Category-Based Cashback
Some cards provide different cashback rates for different spending categories.
For example, a card could offer a higher reward rate on groceries and a lower rate on other purchases.
These cards may be useful for people whose regular spending matches the card’s bonus categories.
Credit Card Points
Points-based credit cards allow you to earn points when you make eligible purchases.
For example, a card might offer one point for every dollar spent, while another may provide multiple points on selected categories.
Points can potentially be redeemed for different rewards, depending on the card issuer.
Common redemption options may include:
- Statement credits
- Gift cards
- Travel
- Merchandise
- Shopping rewards
- Other redemption options offered by the issuer
One important thing to understand is that one point does not necessarily have the same value across every credit card.
A card may allow you to redeem points in different ways, and the value you receive can vary depending on the redemption method.
Therefore, do not choose a points card based only on the number of points advertised.
Airline Miles
Travel credit cards may offer miles instead of traditional cashback.
Miles are generally designed for people who want to use rewards toward travel-related purchases. Depending on the card, miles may be redeemable for flights, hotels, travel bookings, or other travel-related benefits.
For example, imagine a travel card that provides 2 miles for every eligible dollar spent.
If you spend $1,000 on eligible purchases, you could potentially earn 2,000 miles.
However, the exact value of those miles depends on the card’s redemption rules and the travel program involved.
Travel Benefits Beyond Miles
Some travel credit cards provide additional benefits alongside miles.
These may include:
- Travel credits
- Airport lounge access
- No foreign transaction fees
- Travel insurance
- Hotel-related benefits
- Airline-related perks
Premium travel cards may also charge annual fees, so it is important to compare the cost of the card with the value of the benefits you actually use.
What Are Welcome Bonuses?
A welcome bonus is an introductory reward offered to new cardholders who meet specific requirements.
For example, a credit card might advertise a bonus of a certain number of points or miles after spending a specified amount during the first few months.
The important part is understanding the requirements.
A welcome bonus might require you to:
- Apply and get approved for the card.
- Open the account.
- Spend a specified amount within a specific time period.
- Make purchases that qualify under the card’s terms.
The exact requirements vary between credit cards.
Example of a Welcome Bonus
Suppose a card offers 50,000 points after you spend $3,000 within the first three months.
If you normally spend around $1,000 per month on necessary expenses, reaching the requirement may fit naturally into your regular budget.
However, if you normally spend only $500 per month, increasing your spending simply to earn the bonus could create unnecessary debt.
A welcome bonus should generally be treated as an additional benefit rather than a reason to spend money you cannot afford.
Cashback vs. Points vs. Miles
Choosing between different reward types depends largely on how you intend to use your rewards.
| Reward Type | Best For | Main Advantage |
|---|---|---|
| Cashback | Everyday spending | Simple and easy to understand |
| Points | Flexible rewards | Multiple redemption possibilities |
| Miles | Frequent travelers | Travel-focused rewards |
| Welcome Bonus | New cardholders | Potential introductory value |
There is no single reward system that is automatically suitable for everyone.
Someone who wants simple savings may prefer cashback, while someone who frequently travels may be more interested in miles or flexible travel points.
Pay Attention to Reward Categories
Reward rates can vary considerably between purchase categories.
A card might provide a higher reward rate for groceries but a lower rate for general purchases.
Before applying, look at your actual spending habits.
For example, if most of your monthly spending goes toward groceries, gas, dining, or travel, check whether the card provides enhanced rewards in those categories.
Do not choose a card based only on an attractive advertised reward percentage.
Understand Reward Limits
Some credit cards place limits on how much spending qualifies for bonus rewards.
For example, a card could provide a higher reward rate only up to a certain amount of spending during a particular period.
After reaching the limit, purchases may earn a lower standard rate.
Always check the card’s terms to understand:
- Reward limits
- Eligible purchases
- Bonus categories
- Reward expiration rules
- Redemption requirements
- Minimum redemption amounts
These details can affect the real value of a rewards program.
Watch Out for Annual Fees
A rewards card may offer attractive benefits but also charge an annual fee.
For example, imagine a card with a $95 annual fee. If you earn $150 in rewards and receive $50 in benefits that you actually use, the card may provide significant value.
But if you earn only $40 in rewards and rarely use the additional benefits, the annual fee could outweigh the value you receive.
This is why it is important to calculate your potential rewards instead of focusing only on the headline offer.
Never Overspend Just to Earn Rewards
Credit card rewards should not encourage unnecessary spending.
If you spend $1,000 to earn $20 in rewards but then carry the balance and pay significant interest, the cost of borrowing can easily exceed the value of the reward.
A practical approach is to use a rewards credit card for purchases you were already planning to make and pay your statement balance according to your financial situation.
Rewards are most useful when they complement responsible spending rather than encourage additional debt.
How to Get More Value From Credit Card Rewards
You can potentially improve the value of your rewards by matching your credit card with your normal spending habits.
For example, you could:
- Use cashback cards for everyday purchases.
- Use travel cards for eligible travel spending.
- Look for cards with rewards that match your largest spending categories.
- Understand bonus category limits.
- Compare annual fees with expected benefits.
- Read the redemption rules before applying.
- Track welcome bonus requirements carefully.
- Avoid unnecessary purchases just to earn rewards.
Keeping track of your rewards can also prevent points or miles from being overlooked.
Final Thoughts
Credit card rewards can provide useful benefits when you understand how they work. Cashback offers a straightforward way to receive value from eligible purchases, while points can provide flexible redemption options. Miles may appeal to people who frequently travel, and welcome bonuses can provide an additional introductory reward when their requirements are met.
However, the advertised reward rate is only one part of the picture. Annual fees, redemption rules, spending limits, interest charges, and eligibility requirements can all affect the actual value of a credit card.
Before choosing a rewards card, consider your normal spending habits and how you would realistically use the rewards. The goal should be to select a card whose rewards and costs make sense for your personal financial situation.
When used responsibly, credit card rewards can turn regular purchases into additional benefits without requiring you to change your spending habits simply to earn rewards.