When you apply for a credit card, you will often see terms such as APR, interest rate, purchase APR, cash advance APR, and introductory APR. For someone who is new to credit cards, these terms can seem complicated.
Two of the most commonly confused terms are APR and interest rate. Although they are closely related, they are not always used in exactly the same way.
Understanding the difference can help you compare credit cards more carefully and understand what borrowing may cost if you carry a balance from one month to the next.
What Is a Credit Card Interest Rate?
An interest rate is the percentage used to calculate the interest charged on money you borrow.
For a credit card, the interest rate generally determines how much interest can accumulate when you carry a balance instead of paying it according to the card’s terms.
For example, suppose a credit card has an interest rate of 20%.
If you carry a balance, the issuer uses the applicable rate and calculation method described in your credit card agreement to determine the interest charged.
However, simply seeing a 20% rate does not mean you will automatically pay 20% of your balance every month or every year. Credit card interest calculations can be more complicated because issuers may use daily periodic rates and other calculation methods.
What Is Credit Card APR?
APR stands for Annual Percentage Rate.
For credit cards, APR is commonly used to express the annualized cost of borrowing associated with the account’s applicable interest rate.
A credit card can have different APRs for different types of transactions.
For example, a card may have:
- Purchase APR
- Balance transfer APR
- Cash advance APR
- Penalty APR
- Introductory APR
These rates can be different, so it is important to read the card’s terms instead of looking at only one advertised number.
APR vs. Interest Rate: Are They the Same?
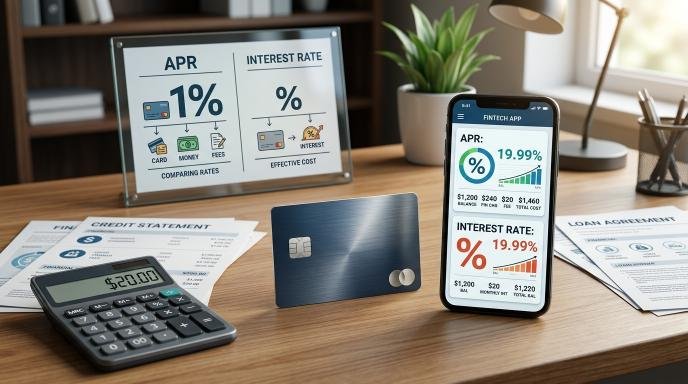
In many credit card situations, people use “APR” and “interest rate” interchangeably because the APR reflects the annualized interest rate used for the credit card.
However, the terminology can be different depending on the financial product.
With credit cards, the APR is especially important because it is the standard rate consumers commonly see when comparing cards.
The key point is this:
The APR helps you understand the annualized rate associated with carrying a credit card balance, while the actual interest charged to your account depends on the issuer’s calculation method and your balance over time.
How Credit Card Interest Is Calculated
Credit card interest is not normally calculated by simply taking your annual APR and charging that amount once per year.
Many credit card issuers calculate interest using a daily periodic rate.
For example, if a card has a 24% APR, a simplified daily rate could be approximately:
24% ÷ 365 = 0.06575% per day
The actual calculation can depend on the issuer’s terms and the type of balance involved.
This is why carrying a credit card balance for several months can become expensive.
Example: Carrying a Credit Card Balance
Imagine you have a credit card with a $2,000 balance and a 24% APR.
A simplified annualized calculation might suggest that 24% of $2,000 is $480.
However, this does not mean the issuer will simply add $480 to your account at the end of the year.
Actual credit card interest depends on factors such as:
- Daily balances
- Payments
- New purchases
- Interest calculation method
- The applicable APR
- Grace period rules
- Other terms in the card agreement
Therefore, the $480 figure should only be viewed as a simple illustration, not an exact prediction of your credit card interest.
Why APR Matters When Choosing a Credit Card
APR becomes particularly important if you expect to carry a balance.
Suppose you are comparing two cards:
| Feature | Card A | Card B |
|---|---|---|
| Purchase APR | 19.99% | 28.99% |
| Annual Fee | $0 | $95 |
| Rewards | 1% cashback | 2% cashback |
| Introductory Offer | Available | Available |
Card B offers higher rewards, but its APR is also higher.
If you always pay your statement balance in full and avoid interest, the APR may have less practical impact on your purchase spending.
But if you regularly carry a balance, the higher APR could increase the cost of borrowing.
This is why rewards should not be considered separately from the card’s costs.
What Is a Purchase APR?
Purchase APR is the interest rate that applies to eligible purchases when interest is charged under the card’s terms.
For example, if you purchase a laptop, groceries, or other products using your credit card and then carry a balance, the purchase APR may apply.
Many credit cards provide a grace period for purchases if you meet the applicable conditions, such as paying the statement balance in full by the due date.
The exact rules vary by card, so always check your cardholder agreement.
What Is a Balance Transfer APR?
A balance transfer APR applies to balances transferred from another credit card or account when the transaction qualifies as a balance transfer.
Some credit cards offer promotional balance transfer APRs for a limited period.
For example, a card may offer a promotional rate for a certain number of months.
However, balance transfers can also involve a balance transfer fee.
Before transferring a balance, calculate the total cost, including:
- Balance transfer fee
- Promotional APR
- Length of promotional period
- APR after the promotional period
- Monthly payments required
A low promotional APR does not necessarily mean the transfer is free.
What Is a Cash Advance APR?
A cash advance allows you to access cash using your credit card.
Cash advances can have a separate APR that is often different from the purchase APR.
They may also involve additional fees.
Before using a credit card for a cash advance, check the card’s terms for:
- Cash advance APR
- Cash advance fee
- ATM fees
- Interest calculation rules
- Cash advance limit
Because cash advances can be expensive, they are generally something to consider carefully rather than treating them like ordinary purchases.
What Is an Introductory APR?
An introductory APR is a temporary promotional rate offered by some credit cards.
For example, a card might offer a promotional APR for purchases or balance transfers for a specified period.
The promotional rate eventually ends, and the regular APR may apply afterward.
Before accepting an introductory offer, make a note of:
- Promotional APR
- Promotion start date
- Promotion expiration date
- Regular APR afterward
- Eligible transaction types
A promotional offer should not be evaluated without considering what happens after the promotional period ends.
APR and Annual Fees Are Different
Another common misunderstanding is thinking that APR includes every credit card fee.
It is important to distinguish the interest rate from other account charges.
A credit card may have:
- Annual fee
- Late payment fee
- Foreign transaction fee
- Balance transfer fee
- Cash advance fee
- Returned payment fee
These charges are separate from the interest that may be charged when you carry a balance.
Therefore, when comparing cards, look at both the APR and the complete fee structure.
How to Reduce Credit Card Interest Costs
The simplest way to reduce purchase interest is to avoid carrying a balance when possible and financially appropriate.
Here are several practical habits:
Pay Your Statement Balance
If your card offers a grace period for purchases and you meet the applicable requirements, paying the statement balance in full by the due date can help you avoid purchase interest.
Avoid Unnecessary Purchases
A credit card should not be treated as extra income.
Only spend what fits within your budget.
Track Your Balance
Checking your account regularly can help you understand how much you owe before the statement arrives.
Set Payment Reminders
A reminder can help you avoid forgetting your payment due date.
Understand Promotional Rates
If you use an introductory APR offer, know exactly when it ends and what rate may apply afterward.
Does a Lower APR Always Mean a Better Credit Card?
Not necessarily.
A credit card with a lower APR may reduce borrowing costs if you carry a balance, but other factors can also matter.
For example, one card might have a lower APR but charge an annual fee, while another might have a higher APR but no annual fee.
Your spending habits and payment behavior can affect which features matter most to you.
If you consistently pay your statement balance in full, rewards, fees, benefits, and other features may be more relevant than the difference between two purchase APRs.
If you frequently carry balances, the APR deserves closer attention.
Final Thoughts
Understanding the difference between APR and interest rate is an important part of managing a credit card responsibly.
APR provides an annualized way to understand the rate associated with borrowing, while the actual interest charged to your account depends on factors such as your balance, payments, applicable APR, and the issuer’s calculation method.
Remember that credit cards can have multiple APRs, including purchase, balance transfer, and cash advance APRs. Promotional APRs may also apply for a limited period.
Before applying for a credit card, look beyond the advertised rewards. Compare the APR, annual fee, other fees, promotional terms, and benefits.
Most importantly, if you use a credit card, understand the payment terms and try to keep borrowing within an amount you can comfortably manage. A clear understanding of APR can help you make more informed decisions and avoid unexpected interest costs.