Choosing a credit card can be difficult when there are hundreds of options available. Credit card companies often advertise cashback, reward points, travel miles, welcome bonuses, low APRs, and other benefits. However, a card that looks attractive on paper may not necessarily be the right choice for your personal spending habits.
The most practical way to choose a credit card is to start with your monthly expenses. Instead of choosing a card simply because it offers a large welcome bonus or a high rewards rate, look at where your money actually goes each month.
For example, someone who spends heavily on groceries may benefit from a card with strong grocery rewards, while someone who travels frequently may prefer a card with travel-related benefits.
Start by Understanding Your Monthly Spending
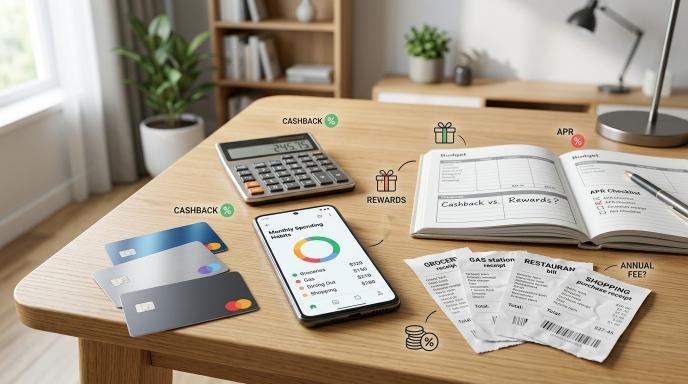
Before applying for a credit card, review your spending for the last two or three months.
Create a simple list of your major spending categories, such as:
- Groceries
- Gas
- Dining
- Online shopping
- Utilities
- Streaming services
- Travel
- Entertainment
- Insurance
- Other everyday purchases
You do not need to track every small purchase manually. A bank statement or budgeting app can help you identify your biggest spending categories.
For example, imagine your monthly spending looks like this:
| Category | Monthly Spending |
|---|---|
| Groceries | $500 |
| Gas | $200 |
| Dining | $150 |
| Online Shopping | $250 |
| Utilities | $200 |
| Entertainment | $100 |
| Other | $200 |
| Total | $1,600 |
This information can help you identify which credit card features may actually be useful.
Look for Rewards That Match Your Spending
Once you understand your spending habits, look for cards that reward the categories where you spend the most.
For example, if groceries make up a large portion of your monthly budget, a card offering enhanced rewards on eligible grocery purchases may be more relevant than a card offering a higher reward rate on travel.
Similarly, if you spend heavily on gas, a card with a strong gas rewards category may provide more practical value.
The goal is simple:
Choose rewards that match your existing spending instead of changing your spending just to earn rewards.
Flat-Rate Cashback Cards
Flat-rate cashback cards are often straightforward because they may provide the same cashback rate on many eligible purchases.
For example, suppose a card provides 2% cashback on eligible purchases.
If you spend $1,500 during a month, your potential cashback could be approximately $30.
This type of card can be convenient for people who do not want to track multiple reward categories.
Who Might Consider a Flat-Rate Card?
A flat-rate cashback card may be worth considering if:
- Your spending is spread across many categories.
- You prefer simple rewards.
- You do not want to activate rotating categories.
- You want predictable rewards.
Always check the card’s terms to understand which transactions qualify for cashback.
Category-Based Rewards Cards
Some credit cards provide different reward rates depending on the purchase category.
For example, a card could provide higher rewards on groceries, dining, gas, or travel and a lower rate on other purchases.
These cards can potentially provide more rewards when your spending matches the bonus categories.
However, category-based cards require more attention.
You may need to remember which purchases receive higher rewards and whether spending limits apply.
Travel Credit Cards
Travel credit cards are designed for people who frequently spend money on travel or want travel-related rewards.
Depending on the card, benefits may include:
- Travel points or miles
- Airline-related rewards
- Hotel benefits
- Airport lounge access
- Travel credits
- No foreign transaction fees
- Travel insurance or protections
However, some travel cards charge annual fees.
Before applying, estimate how much value you would realistically receive from the travel benefits.
If you rarely travel, paying an annual fee for travel benefits you do not use may not make sense for your spending pattern.
Consider the Annual Fee
Rewards are only one part of a credit card’s total value.
A card may offer attractive rewards but charge an annual fee.
For example:
Annual fee: $95
Estimated annual rewards: $180
Benefits you actually use: $40
In this simple example, the total potential value could exceed the annual fee.
But if you earn only $50 in rewards and do not use the card’s additional benefits, the annual fee could reduce or eliminate the value.
Before choosing a card, calculate the potential yearly value rather than focusing only on the advertised reward rate.
Think About Your Payment Habits
Your payment behavior is one of the most important factors to consider when choosing a credit card.
If you normally pay your statement balance in full every month, you may focus more on rewards, fees, and benefits.
If you frequently carry a balance, the card’s APR can become much more important because interest charges may reduce the value of rewards.
For example, earning $20 in cashback does not provide much benefit if you pay significantly more than that in interest because you carry a balance.
A rewards program should never encourage you to spend more than you can afford.
Compare APR Carefully
APR stands for Annual Percentage Rate and is commonly used to describe the annualized rate associated with borrowing on a credit card.
When comparing cards, look at:
- Purchase APR
- Introductory APR
- Balance transfer APR
- Cash advance APR
- APR after promotional periods
If you expect to carry a balance, APR deserves close attention.
If you consistently pay your statement balance in full and qualify for the card’s applicable grace period, the purchase APR may have less impact on your everyday purchases.
Check Foreign Transaction Fees
If you regularly travel outside the United States or purchase goods and services from international merchants, foreign transaction fees may matter.
Some cards charge a percentage of eligible foreign transactions, while others advertise no foreign transaction fees.
For frequent travelers, checking this fee before applying can help avoid unexpected costs.
Look at the Welcome Bonus
Welcome bonuses can be valuable, but they should not be the main reason you choose a credit card.
A typical offer may require you to spend a certain amount within a specified period after opening the account.
For example, imagine a card offers a large number of points after spending $3,000 within the first few months.
If your normal spending naturally reaches that amount, the bonus may be useful.
But if you need to spend money you would not normally spend just to qualify, the bonus may encourage unnecessary purchases.
Check Reward Redemption Options
Two credit cards can both advertise rewards but provide very different redemption options.
Before applying, check whether rewards can be redeemed for:
- Statement credits
- Travel
- Gift cards
- Merchandise
- Direct deposits
- Other options
Also check whether redemption values vary depending on how you use your rewards.
A reward program is more useful when you can redeem your rewards in a way that matches your preferences.
Consider Your Largest Monthly Expense
One useful strategy is to identify your largest recurring spending category.
Suppose your monthly budget is:
| Category | Monthly Amount |
|---|---|
| Groceries | $600 |
| Gas | $150 |
| Dining | $100 |
| Travel | $50 |
| Other | $300 |
Groceries are clearly your largest category.
Instead of choosing a card based on a random advertisement, you could specifically compare cards that offer rewards on eligible grocery spending.
This approach makes the decision more connected to your real financial habits.
Avoid Having Too Many Credit Cards
Having multiple credit cards is not automatically bad, but managing several accounts can become complicated.
Every additional card may mean another:
- Payment due date
- Credit limit
- Reward program
- Fee structure
- Statement
- Account to monitor
For beginners, one well-chosen card may be easier to manage than several cards with overlapping benefits.
If you eventually use multiple cards, make sure you can keep track of all accounts and payment deadlines.
Create a Simple Credit Card Comparison
Before applying, make a comparison table.
| Feature | Card A | Card B | Card C |
|---|---|---|---|
| Annual Fee | Check terms | Check terms | Check terms |
| Cashback | Category-based | Flat-rate | Category-based |
| APR | Check terms | Check terms | Check terms |
| Welcome Bonus | Available | Available | Available |
| Travel Benefits | Limited | Moderate | Extensive |
| Foreign Transaction Fee | Check terms | Check terms | Check terms |
| Best Match | Groceries | General spending | Travel |
The purpose of this comparison is not to find the card with the biggest advertised number. It is to identify which card’s features align with your actual needs.
A Simple Formula for Choosing a Card
You can think about the decision using four basic questions:
Where do I spend the most?
How much will I actually earn in rewards?
What fees will I pay?
How do I normally manage my credit card balance?
If you can answer these four questions, comparing credit cards becomes much easier.
Final Thoughts
The right credit card depends on your individual spending habits, payment behavior, and financial priorities.
Start by reviewing your monthly expenses and identifying your biggest categories. Then compare cards based on the rewards they offer for those categories, along with annual fees, APR, foreign transaction fees, welcome bonus requirements, and redemption options.
Remember that a credit card with the highest advertised rewards is not automatically the best fit for every spending pattern.
The most useful card is one whose costs and benefits make sense for how you actually spend and manage your money.
Most importantly, do not increase your spending just to earn rewards. Use credit cards within your budget, make payments on time, and focus on long-term financial habits rather than short-term promotional offers.