Credit cards can be useful for everyday purchases, emergencies, travel, and building a strong credit history. However, credit card fees can quickly increase the cost of using a card if you do not understand when and why they are charged.
Some of the most common costs include annual fees, late payment fees, foreign transaction fees, balance transfer fees, cash advance fees, and interest charges. The good news is that many of these costs can be reduced or avoided with proper planning.
In this guide, we will explain how credit card fees work and share practical ways to avoid unnecessary charges.
What Are Credit Card Fees?
Credit card fees are charges that a card issuer may apply for specific services, transactions, or account activities. Not every credit card has the same fees, and some cards may waive certain charges.
Common credit card fees include:
| Fee Type | When It May Apply | How to Avoid It |
|---|---|---|
| Annual Fee | Once every year | Choose a no-annual-fee card |
| Late Payment Fee | Payment is made after the due date | Set up automatic payments |
| Foreign Transaction Fee | Purchases made in foreign currencies or outside your country | Use a card with no foreign transaction fee |
| Balance Transfer Fee | Moving a balance from another card | Compare transfer offers carefully |
| Cash Advance Fee | Taking cash from a credit card | Avoid credit card cash advances |
| Returned Payment Fee | Payment is returned or fails | Keep enough money in your bank account |
| Interest Charges | Carrying a balance | Pay the statement balance in full |
Understanding these fees before applying for a card can help you choose an option that matches your spending habits.
How to Avoid Annual Credit Card Fees
An annual fee is a charge that a credit card company may apply once each year simply for keeping the card open. Some premium cards have relatively high annual fees because they offer rewards, travel benefits, airport lounge access, insurance, or other perks.
However, paying an annual fee does not automatically mean that a card is expensive. The important question is whether the benefits you actually use are worth the cost.
Choose a No-Annual-Fee Card
If you do not need premium benefits, consider a credit card with no annual fee.
For example, if one card charges $95 per year while another similar card has no annual fee, the second option may reduce your ongoing costs if you do not use the first card’s additional benefits.
Calculate the Value of Rewards
Before paying an annual fee, calculate how much value you realistically receive from the card.
Suppose a card costs $95 per year but you receive approximately $150 in rewards and benefits that you actually use. The card may provide more value than its fee.
On the other hand, if you only receive $40 in benefits, you may be paying more than you receive.
Ask About Fee Waivers
In some situations, card issuers may offer promotional incentives or retention offers to existing customers. You can contact your card issuer and ask whether there are any available options for reducing or avoiding the annual fee.
There is no guarantee that a fee will be waived, but asking can help you understand your available options.
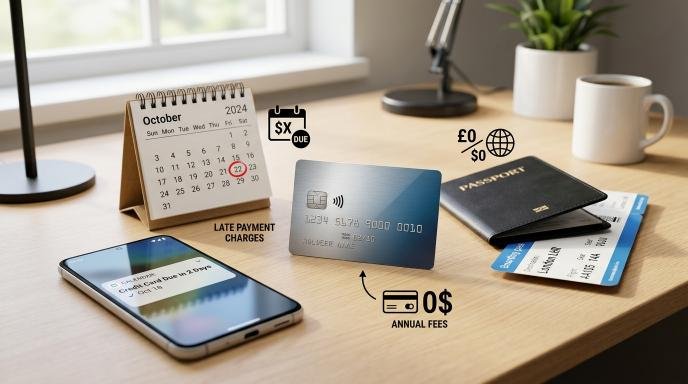
How to Avoid Late Payment Fees
Late payment fees are among the easiest credit card charges to avoid because they are usually connected to a simple issue: missing the payment deadline.
Your credit card statement normally includes a minimum payment amount and a payment due date. Paying at least the required amount by the due date can help you avoid a late payment fee, although paying only the minimum may still result in interest charges.
Set Up Automatic Payments
Automatic payments can reduce the risk of forgetting your due date.
Depending on your card issuer, you may be able to automatically pay:
- The minimum payment
- The statement balance
- A fixed amount
Paying the full statement balance automatically can be especially useful if you have enough money available in your bank account.
Use Payment Reminders
If you prefer to make payments manually, create reminders on your phone or calendar.
For example, you could set one reminder seven days before the due date and another reminder one day before it.
Do Not Wait Until the Last Minute
Online payments may sometimes require processing time. Instead of waiting until the final day, consider making your payment earlier.
This can give you extra time to resolve problems if a payment fails or your bank experiences a technical issue.
How to Avoid Foreign Transaction Fees
Foreign transaction fees can become important when you travel internationally or purchase products and services from companies based in another country.
Some credit cards charge a percentage of the transaction amount as a foreign transaction fee. Even a small percentage can become significant when you make multiple purchases during an international trip.
Choose a Card With No Foreign Transaction Fee
If you frequently travel internationally, look for a credit card that specifically offers no foreign transaction fees.
For example, if you spend $2,000 on eligible international purchases and a card charges a 3% foreign transaction fee, that could add approximately $60 to your costs.
A card with no foreign transaction fee could avoid that particular charge.
Pay in the Local Currency When Appropriate
When using a card abroad, a merchant or payment terminal may sometimes offer to convert the purchase into your home currency.
This is commonly associated with a practice known as dynamic currency conversion.
Before accepting a currency conversion offered by the merchant, check the exchange rate and any additional costs. In many cases, paying in the local currency allows your card network to handle the currency conversion instead.
Avoid Unnecessary Cash Advances
A cash advance allows you to withdraw cash using your credit card. Although this may appear convenient during an emergency, cash advances can come with additional fees and interest costs.
Many cards also treat cash advances differently from normal purchases.
Before using this feature, check your card’s terms for:
- Cash advance fee
- Cash advance APR
- Interest calculation rules
- ATM fees
- Available cash advance limit
If possible, use your bank account or another lower-cost option for obtaining cash.
Be Careful With Balance Transfers
Balance transfers can sometimes help consolidate credit card debt, but they may come with a balance transfer fee.
For example, a card could charge a percentage of the amount transferred. A promotional balance transfer offer may also have a limited introductory period.
Before transferring a balance, calculate the total cost, including the transfer fee and the interest rate that will apply after the promotional period.
Read Your Credit Card Agreement
One of the simplest ways to avoid unexpected fees is to understand the terms of your credit card.
Before applying, review information such as:
- Annual percentage rate (APR)
- Annual fee
- Late payment fee
- Foreign transaction fee
- Balance transfer fee
- Cash advance fee
- Penalty or returned payment charges
- Promotional period terms
Credit card terms can vary significantly between products, so avoid assuming that every card works the same way.
Create a Simple Fee-Avoidance Routine
You do not need a complicated system to manage credit card fees. A simple monthly routine can make a significant difference.
At the beginning of each month, check your credit card balance and upcoming payment date.
During the month, monitor your spending and keep enough money available for your upcoming statement payment.
Before the due date, review your statement and make sure the payment has been scheduled or completed.
If you travel internationally, check whether your card charges foreign transaction fees before using it abroad.
Final Thoughts
Credit card fees are not always unavoidable. Many common charges can be reduced or completely avoided by choosing the right card and developing good payment habits.
A no-annual-fee card may be suitable for someone who does not need premium benefits. Automatic payments can help prevent missed deadlines, while a card with no foreign transaction fee can be useful for international spending.
The most important step is to understand your card’s terms before using it. Instead of focusing only on rewards or introductory offers, consider the complete cost of the card, including fees, APR, and other charges.
By reviewing your credit card regularly, paying on time, and choosing features that match your actual spending habits, you can reduce unnecessary costs and make your credit card more predictable and manageable.